


Malaysia’s federal debt increased by RM441.2 billion between the end of 2020 and the end of 2025. That is a substantial sum. It deserves an explanation that neither exaggerates the danger nor understates the obligations it creates.
The Finance Ministry figures put the debt stock at RM879.6 billion at the beginning of this period and RM1.32 trillion at its close.
A rising debt figure does not, by itself, establish fiscal distress. Equally, a declining deficit does not mean that debt has stopped accumulating. Public confidence requires clear explanation of these distinctions.
Borrowing can support development, while economic growth can improve repayment capacity. But the strength of that relationship depends on what the borrowing finances and how effectively a growing economy generates government revenue. Malaysia’s debt discussion must examine both.
The arithmetic must add up
One explanation circulating in public discussion attributes the increase in debt to development expenditure, with the remainder assigned to pandemic support. The broad proposition is plausible.
Development and emergency assistance both required substantial resources. The precise allocation, however, cannot be established simply by subtracting development spending from the increase in outstanding debt.
A proper reconciliation must account for revenue remaining after operating expenditure, repayments of loans previously extended by the government, expenditure through the Covid-19 fund, changes in cash balances and debt valuation adjustments. Expenditure, annual deficits, net borrowing and changes in the debt stock are related, but they are not interchangeable.
The accounting period matters too. Debt already outstanding at the end of 2020 belongs in the opening balance. An explanation of subsequent accumulation must distinguish existing obligations from additional financing undertaken during 2021–2025.
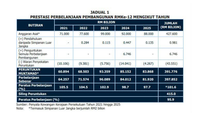
The purpose of this scrutiny is straightforward: the explanation should follow the accounts. An arithmetic remainder cannot, without supporting records, establish where the money went. Transparent reconciliation protects confidence in legitimate spending and makes weaknesses easier to correct.
Gross borrowing also includes funds used to replace maturing debt. When a bond is repaid through an equivalent new issue, the principal effect is refinancing. It does not, by itself, reduce the budget deficit. Similarly, borrowing and fiscal balances must cover matching periods before differences between them can be meaningfully reconciled.
The public deserves an account that connects financing to expenditure and, ultimately, to results.
A development plan is not a debt forecast
The same discipline should govern projections. The RM430 billion development allocation under the 13th Malaysia Plan sets out intended expenditure over 2026–2030. It does not automatically imply RM430 billion in additional debt.
Development can be financed partly from revenue remaining after operating expenditure and from repayments of government loans. Actual borrowing also depends on implementation, revenue performance and cash management.
The Finance Ministry’s original estimates for 2026 illustrate the distinction. Gross development expenditure of RM81 billion became RM79.5 billion after loan recoveries. A projected RM4.9 billion surplus of federal revenue over operating expenditure then reduced the overall deficit to approximately RM74.6 billion.
These original estimates illustrate the accounting relationship; they should not be mistaken for the latest revised fiscal position.

Adding RM430 billion to the end-2025 debt stock therefore produces a conditional scenario of approximately RM1.75 trillion by 2030. It does not establish a forecast.
A credible projection must show the annual financing assumptions connecting the starting debt stock to the eventual outcome.
A smaller deficit still creates financing needs. A falling deficit-to-GDP ratio can therefore coexist with rising debt. Whether that debt remains manageable depends on economic growth, financing costs and the government’s capacity to collect revenue.
Guarantees require similar precision. Direct federal debt, commitments already requiring government support and contingent liabilities should be distinguished.
Guarantees can expose future budgets to additional costs, but treating every guarantee as an immediate federal debt obligation would obscure the nature of the risk.
Confidence must be earned
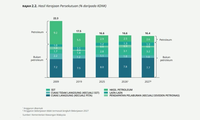
The revenue side deserves greater attention. The Finance Ministry’s revenue composition chart shows federal receipts falling from 22.3 percent of GDP in 2009 to a baseline estimate of 16.4 percent in 2027. Petroleum-related revenue accounts for the principal change, declining from 9.2 to 2.6 percent of GDP. The 2027 estimate excludes the effects of new budget measures.
By subtraction, non-petroleum revenue increases from approximately 13.1 to 13.8 percent of GDP. That modest improvement leaves much of the reduced petroleum contribution unreplaced. These figures describe revenue relative to the economy; they do not imply that receipts have fallen continuously in ringgit terms.
This distinction is consequential. A larger economy can support a lower debt ratio while the government collects a smaller share of national income. Growth remains essential, but its fiscal benefits depend on the composition of activity, the tax framework and effective collection. The Treasury’s capacity to finance service cannot be inferred from GDP growth alone.
The consequences are tangible. Projected debt service charges of approximately RM61 billion in 2027 represent about 13.3 percent of federal expenditure and 16 percent of projected revenue. These commitments narrow the resources available for other priorities, even when debt remains serviceable.
Credit ratings provide valuable external assessments. S&P’s sovereign methodology considers debt relative to GDP, interest costs relative to government revenue, and the structure and accessibility of financing. A maintained rating offers reassurance about creditworthiness; it does not remove fiscal constraints.
For households, those constraints become real through choices about healthcare, education, infrastructure and emergency assistance. Fiscal discipline must therefore encompass dependable revenue as well as careful spending. Better compliance, scrutiny of ineffective tax concessions and a broader revenue base should proceed alongside protection for vulnerable households.
Expenditure quality remains central. Schools, hospitals and transport infrastructure can strengthen productive capacity and public welfare. Their value depends on sound selection, competitive procurement, timely completion and adequate staffing and maintenance. A development classification does not guarantee a worthwhile return.
Borrowing can protect livelihoods during a crisis and finance benefits extending across generations. Future Malaysians will inherit both the obligations incurred today and the assets they finance. Our responsibility is to ensure that those assets and their benefits justify the obligations.
The appropriate response is neither panic nor complacency. It is disciplined scrutiny: of what is borrowed, what it finances and what it delivers. The strongest reassurance is a government that can demonstrate that today’s debt is building tomorrow’s capacity to prosper - and to pay. - Mkini
SAMIRUL ARIFF OTHMAN is an economist and adjunct lecturer with Universiti Teknologi Petronas.
The views expressed here are those of the author/contributor and do not necessarily represent the views of MMKtT

No comments:
Post a Comment
Note: Only a member of this blog may post a comment.