


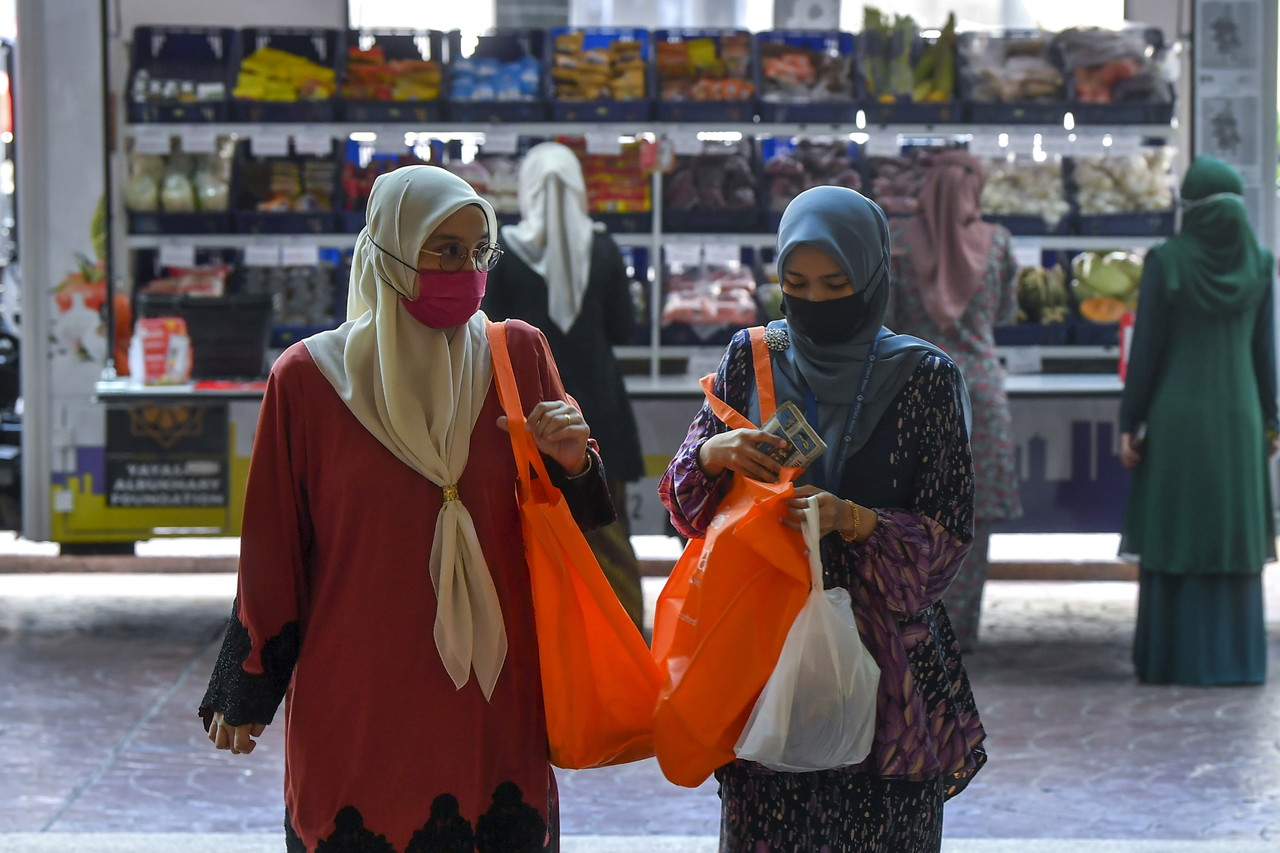
MALAYSIA should not settle for helping the middle class cope with the rising cost of living. It should aim to build an economy where fewer families remain poor and more can achieve lasting financial security. That is the real test of Budget 2027.
Deputy Finance Minister Liew Chin Tong’s call to build a middle class larger than the B40 captures an important national goal. But the challenge goes well beyond tax relief, cash aid and subsidies.
These measures may ease household pressures today, but they cannot guarantee Malaysians will be better off tomorrow.
There is also an important distinction to make. Under Malaysia’s usual household income classification, B40 refers to the bottom 40% of households, M40 the middle 40% and T20 the top 20%.
These are statistical groupings, not fixed measures of poverty or middle-class living standards. The M40 cannot numerically exceed the B40 while these percentile-based definitions remain unchanged.
The more meaningful goal is to help more B40 households achieve middle-class living standards through decent wages, stable jobs, affordable housing, adequate savings and access to quality education and healthcare.
Just as importantly, M40 households must be protected from sliding into financial insecurity as living costs rise.
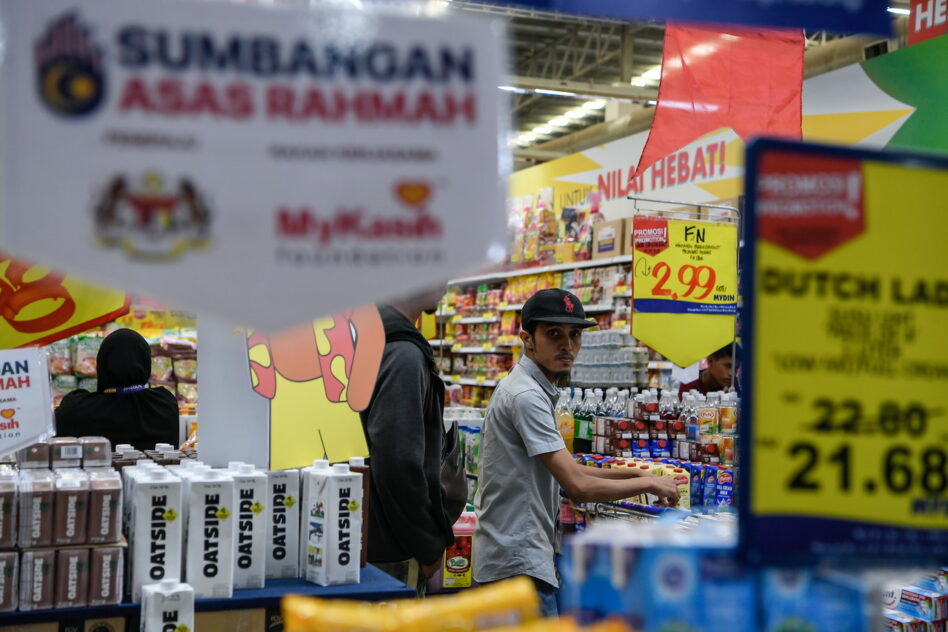
The question is not simply whether Budget 2027 offers enough relief. It is whether the budget lays the foundation for more Malaysians to escape financial vulnerability for good.
The budget raises individual income tax relief from RM9,000 to RM12,000 and reduces resident individual income tax rates by one percentage point for certain income bands.
It also provides SARA MADANI assistance, continues the My50 public transport pass and introduces MyKomuter50 for KTM Komuter users.
The government has proposed extending stamp duty exemptions for first-time homebuyers, including full exemptions for qualifying homes priced up to RM500,000 and partial relief for homes costing up to RM750,000. These are useful steps.
Still, the benefits will vary considerably between households. Tax relief mainly helps those who pay income tax, while temporary cash assistance cannot permanently compensate for rising food, healthcare, childcare and housing costs.
A home may qualify for a stamp duty exemption yet remain unaffordable once the deposit, monthly instalments and maintenance are factored in.
The government must therefore distinguish between helping households survive the present crisis and creating the conditions for them to prosper.
The central issue is purchasing power.
Malaysia’s Household Income Survey 2024, published by the Department of Statistics Malaysia in October 2025, reported a median monthly household income of RM7,017.
Nominal household incomes rose, but the decisive question is whether earnings are growing faster than the essential costs families must bear.
A household receiving a 3% pay rise while its essential expenses climb 6% becomes financially weaker, even though its nominal income is higher.
That is why GDP growth and wage increases alone cannot tell us whether ordinary Malaysians are becoming more prosperous.
The government must prioritise productivity-led wage growth. Businesses should be encouraged to invest in technology, worker training and higher-value activities, with productivity gains translating into better salaries.
Small and medium-sized enterprises, which employ workers across the economy, need access to technology, financing and skills development to move beyond low-wage business models.
Education reform is equally important. Malaysia cannot build a prosperous middle class if graduates struggle to find suitable work while employers report skills shortages.
Educational success must be measured not just by examination results and qualifications, but also by critical thinking, employability, productivity and the ability to adapt to changing economic conditions.
Housing and social protection must become pillars of middle-class security.
Home ownership should not be promoted through tax incentives alone. Housing policy must tackle the mismatch between property prices, household earnings and the places where jobs are located.
Affordable homes near reliable public transport and workplaces would deliver more lasting benefits than incentives that leave households burdened by excessive debt.
Healthcare, childcare, retirement savings and protection against unemployment matter too. A family may fall within the M40 category yet remain financially fragile because it supports elderly parents, pays for childcare and carries substantial housing loans. Income classifications alone cannot capture these vulnerabilities.
The government should publish annual indicators measuring real disposable income after inflation, housing affordability, household debt, savings, productivity and social mobility.
It should also track how many households move out of persistent financial hardship and achieve sustained improvements in living standards.
The timeline must be realistic. Immediate relief can take effect within one or two years. Significant improvements in household financial security may take three to five years, while transforming the economy towards higher productivity and better-paying jobs could take five to 10 years or longer. These are indicative policy horizons, not guaranteed forecasts.
Ultimately, Malaysia should aspire to a society where fewer families struggle to meet basic needs and more can build secure, independent lives through decent jobs, quality education and affordable public services.
Budget 2027 may be a step in the right direction. The real test is whether assistance becomes a bridge to economic independence rather than a recurring substitute for structural reform.
A prosperous nation is not one that keeps expanding its assistance programmes, but one that progressively enables more citizens to live securely without needing emergency help.
That should be the measure of Malaysia’s success in building a stronger middle class.
KT Maran is a Focus Malaysia reader.
The views expressed are solely of the author and do not necessarily reflect those of MMKtT
- Focus Malaysia.

No comments:
Post a Comment
Note: Only a member of this blog may post a comment.