


THE consumer products sector remains defensive despite softer consumer sentiment and rising operating costs, with RHB maintaining its “Overweight” rating as valuations become increasingly attractive.
The research house expects earnings to remain resilient, supported by healthy employment conditions, wage growth and continued government assistance.
On that note, RHB favours companies with stronger Minimum wage hike poses earnings risks for retailers despite spending boostdemand visibility, pricing power and greater exposure to lower-income consumers.
Budget 2027 is expected to support earnings in the financial year 2027, particularly among essential goods retailers and value-focused chains.
The government’s RM16 bil allocation for the Sumbangan Tunai Rahmah (STR) and Sumbangan Asas Rahmah (SARA) programmes, alongside personal income tax relief measures, should help sustain household spending.
Although total assistance for most households remains broadly unchanged, a larger SARA component will direct more spending towards eligible essential goods.
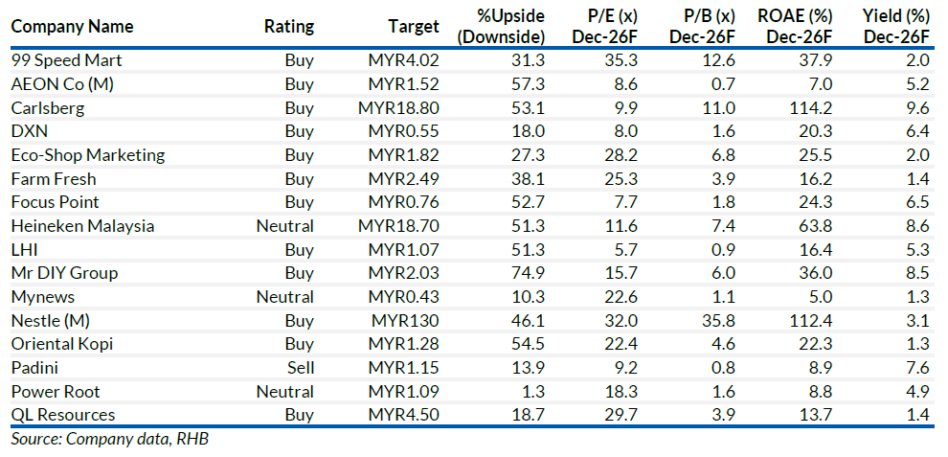
This should benefit participating retailers such as 99 Speed Mart, Eco-Shop and Mr DIY Group through higher store sales and improved fixed-cost absorption.
The minimum wage is also set to rise 17.6% from RM1,700 to RM2,000 from June 2027. While this could improve purchasing power, RHB cautioned that higher payroll expenses would weigh on retailers before additional consumer spending benefits materialise.
A 5% increase in total wage costs could reduce earnings by 3.4% to 5.3% for selected retailers under its coverage.
Meanwhile, aggressive pricing by foreign e-commerce platforms presents competitive pressure, particularly for smaller resellers of generic imported goods.
However, RHB believes established retailers such as Mr DIY and Eco-Shop can remain competitive through extensive store networks, procurement scale and convenience.
Proposed e-commerce regulations could also improve competitive fairness.
For its top picks, RHB sees 99 Speed Mart and Nestle benefiting from stronger essential-goods demand and brand loyalty.
Eco-Shop offers growth potential through further expansion, while QL Resources could benefit from improving marine product manufacturing and integrated livestock farming conditions.
Key risks identified by RHB are such as the prolonged geopolitical tensions, major supply chain disruptions and persistently weak consumer sentiment.— Focus Malaysia

No comments:
Post a Comment
Note: Only a member of this blog may post a comment.